 By Alexa Gavin
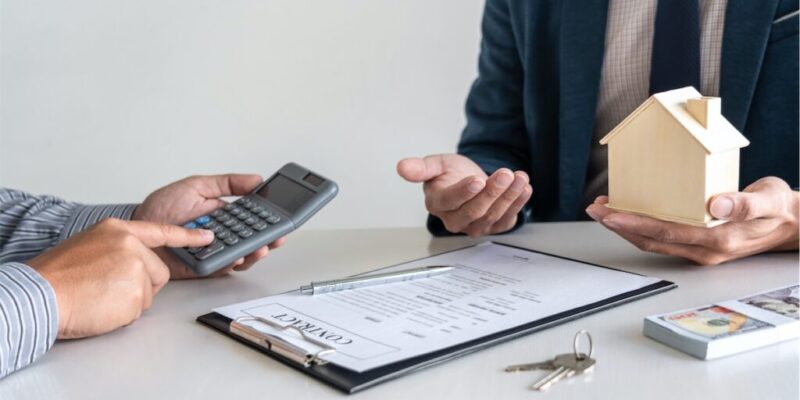
Securing pre-approval for a home loan is an essential step for many prospective homeowners. It provides clarity on how much you can borrow, strengthens your position when negotiating with sellers, and streamlines the home-buying process. However, many find the concept of pre-approval confusing or intimidating. Understanding what pre-approval entails, its benefits, and the steps involved can empower buyers to approach their home purchase with assurance.
This guide unpacks the fundamentals of home loan pre-approval, explaining its significance, what it requires, and how it aids in navigating the real estate market effectively.
What Is Home Loan Pre-Approval?
Home loan pre-approval is a formal acknowledgment from a lender indicating that you meet the basic requirements to qualify for a mortgage. Based on your financial situation, the lender estimates the loan amount they are willing to offer.
Key Features of Pre-Approval
- Conditional Approval: Pre-approval is not a final loan agreement but a conditional assurance, subject to specific criteria such as property valuation.
- Loan Estimate: It provides clarity on the potential loan amount, interest rate, and estimated monthly payments.
- Validity Period: Most pre-approvals remain valid for 60 to 90 days, giving you a window to search for a property within your budget.
Benefits of Home Loan Pre-Approval
Securing pre-approval offers several advantages, enhancing both your financial understanding and your position in the housing market.
Clear Financial Boundaries
Pre-approval defines the price range you can afford, allowing you to focus your property search on homes within your means. It eliminates the risk of falling in love with a property beyond your budget.
Stronger Buyer Position
In competitive markets, sellers often prioritize buyers with pre-approval. It signals that you are a serious buyer with financing already assessed, giving you an edge in negotiations.
Faster Closing Process
Since much of the financial vetting is completed during pre-approval, the formal loan approval process becomes quicker once you’ve found a property.
Identification of Issues Early On
Pre-approval highlights any financial challenges or gaps that might hinder your loan application. This early insight provides time to address issues before making offers on homes.
The Pre-Approval Process
While the exact steps may vary between lenders, the process typically follows a structured path:
1. Gather Financial Documents
The lender will request documentation to assess your financial health. Commonly required documents include:
- Proof of income (e.g., pay stubs or tax returns).
- Bank statements to verify savings and account balances.
- Credit history and credit score.
- Identification documents.
2. Submit a Pre-Approval Application
After gathering the necessary paperwork, you’ll complete a formal application. This allows the lender to evaluate your financial standing and determine how much they can potentially lend you.
3. Undergo Credit and Financial Assessment
The lender reviews your credit history to gauge your ability to repay the loan. Additionally, they assess your debt-to-income ratio, employment stability, and savings.
4. Receive the Pre-Approval Letter
If the lender approves your application, you’ll receive a pre-approval letter. This document outlines the maximum loan amount you qualify for and other terms. Sellers and real estate agents often view this letter as evidence of your buying capability.
Factors That Affect Pre-Approval
Several elements influence the lender’s decision-making process during pre-approval:
Credit Score
A higher credit score typically results in better loan terms. Lenders view strong credit as an indicator of responsible financial behavior.
Debt-to-Income Ratio
This ratio compares your monthly debt payments to your monthly income. A lower ratio demonstrates a manageable debt load, increasing your likelihood of approval.
Employment Stability
Lenders prefer borrowers with steady employment, as it reflects reliable income for loan repayment. Gaps in employment or frequent job changes may raise concerns.
Savings and Down Payment
Having sufficient savings for a down payment reassures lenders of your financial preparedness. Larger down payments may also reduce the required loan amount.
Tips to Strengthen Your Pre-Approval Application
1. Improve Your Credit Score
Check your credit report for inaccuracies and aim to reduce outstanding debts. Consistent on-time payments can also boost your score.
2. Save Aggressively
Building a robust savings account not only aids in meeting down payment requirements but also enhances your financial stability in the lender’s eyes.
3. Avoid Major Financial Changes
Refrain from making large purchases, opening new credit accounts, or changing jobs during the pre-approval process. These actions can alter your financial profile and affect the lender’s assessment.
4. Shop for Lenders
Different lenders may offer varying loan terms and pre-approval criteria. Comparing options ensures you secure the most favorable terms.
Common Misconceptions About Pre-Approval
1. Pre-Approval Guarantees a Loan
It’s important to recognize that pre-approval is not a final loan commitment. Final approval depends on factors like the property’s value and meeting additional criteria.
2. Pre-Qualification Equals Pre-Approval
While pre-qualification provides a rough estimate of your borrowing power, pre-approval is a more rigorous process, carrying greater credibility in the market.
3. Pre-Approval Letters Are Fixed
Loan terms outlined in the pre-approval letter can change if your financial circumstances shift. Keep your finances stable during the validity period.
A Thoughtful Step in the Home Buying Process
Home loan pre-approval is more than a preliminary step—it is a strategic tool for navigating the housing market with confidence. By understanding its requirements and benefits, you position yourself as a knowledgeable and prepared buyer, ready to make offers with conviction. This proactive measure not only simplifies the buying process but also fosters a sense of control in what is often considered one of life’s significant financial decisions.