 By Alexa Gavin
Fixed deposits are one of the many ways to earn extra money out of extra cash in hand. They are not only secure but provide regular income. It is a safe method to let your money grow. Different banks give different interest rates and pay a little extra for senior citizens.
But are you leveraging your fixed deposit to earn the maximum? Portfolio management is to have a mix of investment options on your plate. The appropriate ratio of different kinds of investment depends on your risk appetite and long-term financial goals.
Are you getting the maximum out of the investment options available to you? Once you read this article, you will know multiple options to grow money from the fixed deposit in your account. You need to understand the fixed deposit laddering strategy to help you earn some extra income.
What Is Fixed Deposit Laddering?
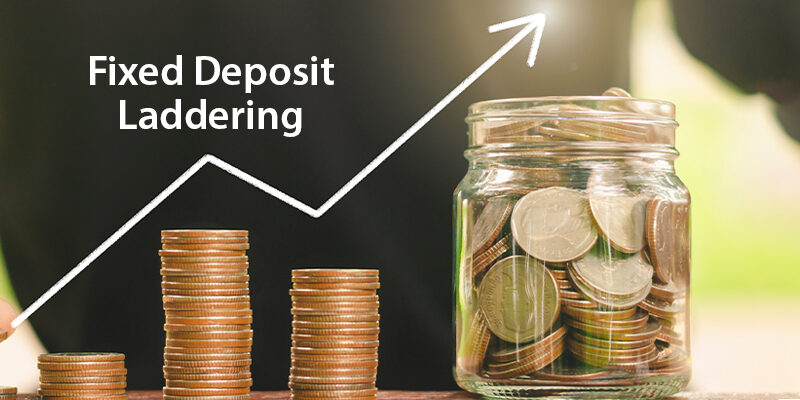
Fixed deposit laddering is to break the lumpsum amount in the FD account and invest in different small FD accounts. Different FDs may have different maturity periods. It helps you earn a fixed amount at different maturity dates. Your money will grow steadily to give fixed returns at regular intervals. You may check your balance online.
How Does FD Laddering Work?
Each step in the ladder represents a different period and helps you by not committing a single amount in one FD. Different FDs earn different money as the interest rate varies at distinct periods. The ROI will go on increasing as you climb up the ladder.
For example, a bank lends five lakhs, and the ROI is 5.2% in 2022. The interest rate during September 2023 has gone up to 6.5. You will lose out on extra interest if you lock in a large amount in the earlier FD. You may reinvest the amount after maturity to earn a higher interest rate.
Benefits Of Fixed Deposit Laddering:
A one-year fixed deposit would not have the same impact as five years because you should benefit from the RBI’s hiked interest rates. You have the following benefits:
- Liquidity Benefits:
When you follow a fixed deposit laddering strategy, you may have at least one FD maturing at the end of each year. You may have liquid cash if you break the amount and invest it. But the premature withdrawal of money would attract a penalty, and you would lose on the interest rates.
- Handling Interest Rate Risk:
Since different FDs have staggered maturity dates, you can handle fluctuating interest rates. You may reinvest the maturity amount at higher rates of interest. Investing in FDs with higher rates is possible even when there is a decrease in interest rates by RBI.
- Financial Discipline:
FD laddering requires the investors to maintain discipline. It deters you from withdrawing money before maturity and promotes long-term financial planning.
Verdict:
Fixed deposits earn a fixed interest rate and have a fixed maturity date. Unlike share market investments, they don’t lead to capital corrosion. You may check the transaction history in your profile online. Fixed deposit laddering means investing different amounts at different periods at varied interest rates. These return enhancement tactics will not work when there is a fall in interest rates in a particular year.